My Brother-in-Law Wants to Buy a Rental at 6.7%. I Told Him to Run the Numbers First.
Thanksgiving was awkward this year. Dave — my brother-in-law, not the stuffing — announced he was buying a duplex in Aurora as a rental property. "Rates are going to drop next year," he said. "I will refinance then." I put down my fork. I asked him what rate he was locking. He said 6.7%. I asked him what the property cash-flowed at that rate. He said, "It basically breaks even. But appreciation will make up for it."
I love Dave. But that is not investing. That is speculation with a mortgage.
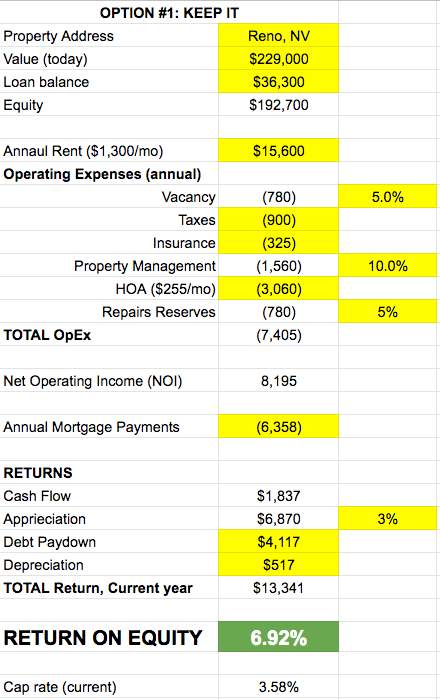
Here is the math he did not do. A $400,000 duplex with 20% down means an $80,000 cash investment plus about $10,000 in closing costs. The loan is $320,000 at 6.7% over thirty years. Principal and interest alone: $2,060 per month. Taxes and insurance in Aurora? Another $550. Maintenance reserve at 5% of gross rent? $200. Property management? $250. Total monthly carrying cost: $3,060. He thinks he can rent each unit for $1,500. That is $3,000 gross. He is underwater by $60 a month before a single toilet breaks.
The appreciation argument drives me nuts. Yes, Colorado real estate has appreciated historically. But past performance does not pay this month's mortgage. If Dave loses a tenant for sixty days, he is out $3,000 in lost rent plus the $3,060 carrying cost. That is a $6,000 hole. How many months of "appreciation" does it take to fill that? At 3% annual appreciation on $400,000, he gains $12,000 a year in equity. One vacancy and one HVAC repair eats half of that.
I showed him the fee comparison tool on my site. If he took that same $90,000 and put it into a diversified portfolio with a 0.03% expense ratio instead of a rental property with hidden costs, the difference over ten years is staggering. No 3 AM phone calls about a leaking water heater. No eviction courts. No property tax hikes. Just compound growth doing its boring, beautiful thing.
Dave pushed back. "But I want tangible assets." I get it. I really do. I own my home. I like tangible too. But a rental property that loses money every month is not an asset. It is a liability wearing a landlord costume.
The 6.7% mortgage rate is not the enemy. The enemy is buying a property that does not cash-flow at today's rates while hoping tomorrow's rates will save you. That is not a strategy. That is a prayer. And I do not manage money based on prayers. I manage it based on spreadsheets.
Dave is still buying the duplex. I told him I hope I am wrong. I also told him to keep three months of carrying costs in cash reserves and to never call me at 2 AM when the tenant's shower backs up. He laughed. I did not. I have seen this movie before. The ending is expensive.
Marcus Thornton, Denver
