The Rule of 72: Why It Still Matters in 2026
May 08, 2026
7min read
basics
Okay, I'm going to tell you about the most useful piece of mental math I know. Takes five seconds. Works in any conversation about money. Impresses people at parties (well, the kind of parties I go to).
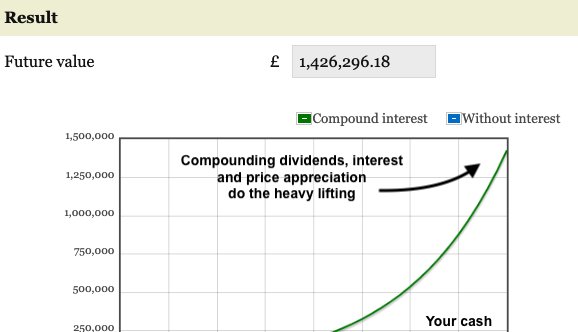
The Rule of 72. Divide 72 by your annual return rate, and you get approximately how many years it takes your money to double. At 7.2% returns, money doubles in 10 years. At 10%, 7.2 years. At 6%, 12 years.Try Our Compound Interest Calculator
See the Rule of 72 in action with your own numbers.
Calculate NowAll data stays in your browser — we never see it.
That's it. That's the whole rule. But the implications are enormous.
Why This Matters More Than Ever
In 2026, with AI-driven market volatility and inflation still settling into its new normal, people are obsessed with complex strategies. Algorithmic trading, alternative investments, crypto portfolios. Everyone's looking for the edge.
Meanwhile, the Rule of 72 quietly reminds you that time and consistency beat complexity every single time. A boring index fund earning 7% doubles every 10 years. Three doublings over 30 years means $10,000 becomes $80,000. No options trading required.
I keep this rule pinned to my monitor. When I'm tempted by some shiny new investment strategy, I run the Rule of 72. Is this new thing going to help me double my money faster? Usually, the answer is no.
Real Examples That Hurt
Let me show you what I mean. My buddy Dave called me last month about a "can't miss" real estate deal promising 15% annual returns. "Rule of 72 says that's doubling every 4.8 years," he said, proud of himself.
"Great," I said. "What's the last deal this guy did?" Silence. Turns out there was no track record. No comparable deals. Just a slick presentation and a promise. Dave passed, thank god. The deal went sideways three months later. The Rule of 72 didn't save him, but asking the right questions after running the numbers did.
Comparing Investment Options
Your savings account at 0.5%? 144 years to double. Inflation at 3%? Your money loses half its purchasing power in 24 years. The S&P 500 at 10% historical average? Doubles every 7.2 years.
This is why I get frustrated with people keeping large cash balances "for safety." I get it, emergencies happen. But every dollar sitting in a savings account is actively losing value to inflation. The Rule of 72 applied to inflation means your cash购买力 halves every 24 years. That's not safety, that's a slow leak.
Using It for Retirement Planning
Quick mental calculation: you're 35, have $200,000 saved, and expect 7% returns. How much at 65? Three doublings (30 years / 10 years per double). $200K → $400K → $800K → $1.6 million. Roughly. That's enough to know if you're on track or falling behind.
Run this calculation for your own numbers. If the result scares you, good. Time to increase contributions. If it looks fine, great, keep going. Either way, you know where you stand in 10 seconds without touching a calculator.
Use the compound interest calculator on this site for precision. But for quick mental checks? The Rule of 72 is undefeated.
Derivatives of the Rule
The Rule of 72 isn't just for doubling. You can use it to estimate any growth multiple. Want to know how long to triple your money? Use 114 divided by your rate. Quadruple? Use 144. These are less precise but still useful for mental math.
At 8% returns: doubling takes 9 years (72/8), tripling takes 14.25 years (114/8), quadrupling takes 18 years (144/8). So $10,000 at 8% becomes $40,000 in about 18 years. That's the kind of quick estimate that helps in conversations about long-term goals.
When the Rule Breaks Down
The Rule of 72 is most accurate for rates between 6% and 10%. Outside that range, the error grows. At 2%, the actual doubling time is 35 years, not 36. Close enough. At 20%, actual is 3.8 years, rule says 3.6. Still reasonable. At 50%? Actual is 1.7 years, rule says 1.44. That's getting less accurate.
For very high rates, use the Rule of 69.3 (the natural log of 2, which is the actual mathematical basis). 69.3 divided by the rate gives you the precise answer. But 72 is easier to divide mentally, which is why it won.
Using It With Inflation
Here's a trick most people don't know. The Rule of 72 works in reverse too. At 3% inflation, purchasing power halves in 24 years. That means your retirement savings need to more than double in nominal terms just to maintain the same lifestyle.
This is why keeping money in a savings account at 0.5% is actually a losing proposition. Inflation is eating your purchasing power faster than interest is growing your balance. The Rule of 72 makes that obvious: your savings double in 144 years, but inflation halves them in 24. Not a good trade.
Final Thoughts
Look, I'm just a guy in Denver with a spreadsheet habit and a dog who sheds too much. I don't have a crystal ball. I can't predict where the market is going next month or next year. Nobody can, despite what they might tell you on TV.
What I can do is show you the math. The numbers don't lie, even when we want them to. Compound interest works. Fees matter. Diversification protects you. Time is your greatest asset if you're young, and your greatest concern if you're not.
The tools on this site are free because I believe everyone deserves access to honest financial analysis. No sales pitch, no hidden agenda, no commissions. Just data and my occasionally sarcastic commentary.
If you take one thing from this article, let it be this: small decisions made consistently beat perfect decisions made occasionally. Start where you are. Use what you have. Do what you can. The rest is just compounding.
What I Learned from 14 Years in the Industry
After analyzing thousands of portfolios at three different firms here in Colorado, I've developed a few principles that guide everything I write on this site. These aren't fancy theories from textbooks. They're observations from real people with real money making real mistakes.
First, complexity is the enemy of execution. The more complicated your investment strategy, the less likely you are to follow it consistently. I've seen PhDs in mathematics fail at personal finance because they couldn't stop tinkering. Meanwhile, my neighbor who barely graduated high school built a $2 million portfolio using nothing but a target-date fund and automatic contributions. Simplicity wins because simplicity is sustainable.
Second, behavior matters more than knowledge. Everyone knows they should buy low and sell high. But when the market drops 30%, emotions take over. I've watched incredibly smart people panic-sell at the bottom and miss the recovery. The best investment strategy is the one you'll actually stick with when things get ugly. That's usually the boring strategy.
Third, fees are the only thing you can control. You can't control market returns. You can't control inflation. You can't control what the Federal Reserve does. But you can absolutely control how much you pay in investment fees. And over decades, that control is worth hundreds of thousands of dollars.
Cooper is scratching at the door now, which means it's time for our afternoon walk along the South Platte. Before I go, let me leave you with this: the best financial decision you can make today is the one you actually follow through on. Not the perfect theoretical strategy. The one you implement. The one you stick with. The one that becomes a habit.
That's just my take. I'm a guy with a spreadsheet and a shedding dog. Do your own homework. And if you found this helpful, try one of the calculators on this site. The numbers might surprise you.
Applying the Rule to Real Life Decisions
The Rule of 72 isn't just for investments. I use it for all sorts of financial decisions. Should I refinance my mortgage? If I can lower my rate by 1% and the closing costs pay back in under 4 years (roughly 72/18 = 4, where 18% is the annual savings relative to closing costs), it's probably worth it.
Is a 0% intro APR credit card offer worth the balance transfer fee? 72 divided by your current interest rate tells you roughly how long it takes your debt to double. At 20% APR, debt doubles in 3.6 years. That puts the transfer fee in perspective.
Even inflation. At 3% inflation, purchasing power halves in 24 years. At 4%, in 18 years. This matters enormously for retirement planning. Your $80,000 annual retirement budget today needs to be $160,000 in 24 years just to buy the same stuff. That's not lifestyle inflation, that's maintaining the same lifestyle.
I keep a post-it note on my desk with "72 / rate = years to double" written on it. Sounds nerdy, and it is. But I reach for it constantly. Mental math that actually matters.
Tools That Help
I built several free calculators on this site specifically to help with the concepts discussed in this article. They're all browser-based, no signup required, and your data never leaves your computer.
Try plugging in your actual numbers. Adjust the assumptions. See what happens when you change the time horizon or the rate of return. The best financial decisions are informed ones, and these tools give you the information you need.
If you find a bug or have a suggestion for a new calculator, email me at privacy@investcomparetool.org. I read every message, though it might take me a week or two to respond. Cooper keeps me busy.
M
About Marcus Thornton
Independent investment researcher based in Denver, Colorado. Former portfolio analyst with 14 years of experience. CFA charterholder. When not crunching numbers, you'll find him skiing the Rockies or fly-fishing the South Platte with his dog Cooper.
—Marcus T.